Tuesday's drop was a second discounting of a problem the company disclosed in July. The guidance cut on July 29 to a 4-6% decline in domestic same-store sales was the information; national traffic data for August confirmed the environment rather than the company [4][1]. What has not changed is the part of the model that the stock's valuation has historically rested on: 16% unit growth, 102 net openings in the quarter, a franchised system with $1.9 million average unit volumes and a $1.2 billion securitized debt stack that requires royalty cash flow, not traffic growth, to service [4][5]. The question is whether the market is now pricing the franchise model or the traffic print.
Wingstop: A 52-Week Low on Somebody Else's Traffic Data
AI summary
Wingstop fell 12.1% to a 52-week low after third-party data showed August dining traffic down 2.4%. The research note views this as a second reaction to weak sales, following the company's July guidance cut for a 4-6% same-store sales decline. The stock's valuation still relies on 16% unit growth and $1.9 million average store volumes.
Historical data for similar sharp drops shows a wide 5-session range, with excess returns versus the market between -9.1 and +11.3 points, rising 57% of the time. The strongest other reading points to the broader restaurant sector environment. The next checkpoint is the stock's performance by the close on September 22.
1. The state
At the September 15 close WING was $100.84, -12.1% on the day on 2.9 million shares, a 52-week low, in the memory's state "down/below/off/stuck/effort/weak/crowd_in": a sharp break below reference levels on heavy volume with weak momentum and crowded participation [6][7]. Tuesday's move is inside the state being scored. The pre-market print at 11:31 UTC on September 16 was $101.70, +0.9%, an.
2. What's new
The proximate catalyst was third-party data: Placer.ai's August report showed nationwide dining traffic down 2.4%, relayed by the wire on the morning of September 16 as the reason for Tuesday's decline [1].
3. What that does to the state
The company's own numbers are the baseline.
| Vs the market, in points | Low | Middle | High | Share up |
|---|---|---|---|---|
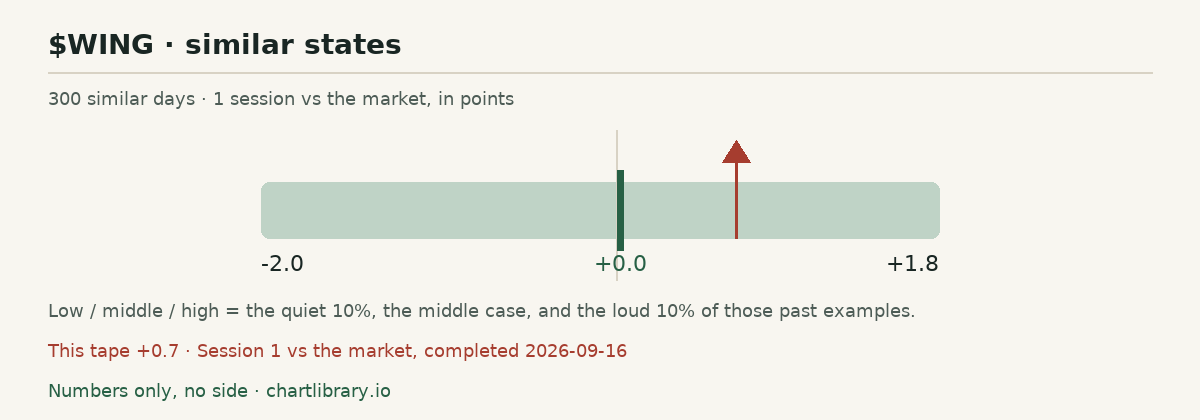
| 1 session | -2.0 | +0.0 | +1.8 | 51% |
| 5 sessions | -3.7 | +0.7 | +4.5 | 62% |
| 10 sessions | -5.1 | +0.1 | +4.8 | 53% |
4. Same state, or a new one
Stayed in yesterday's neighborhood
Session 1 vs the market: +0.7. Prior-state 1-session range: -2.0 / +0.0 / +1.8.
When we look again
Session 1: the completed September 16 session, written up after the close (Federal Reserve decision at 14:00 ET is a confounder). Session 5: September 22. Session 10: September 29. Company: third-quarter results in late October; any update to unit-growth guidance. The Placer.ai report itself was not read directly and its methodology is not verified by us; that is disclosed as a gap. The issuer's press-release index and presentations page were not machine-readable by our scanner at the check time; issuer statements that morning beyond the cited filings are a coverage gap.
Other reading, tape, and sources
The other reading
The case for the market is that a franchisor whose comparable sales are falling 7.5% is a unit-growth story only until franchisees stop opening units, and that national traffic falling in August, with the stock at a 52-week low and a target cut a week earlier, says the decline has not troughed [1][2][4]. The digital share above 70% means Wingstop's customer is the same delivery-app customer whose spending the traffic data captures. The case against is that the July guidance already assumed a 4-6% decline, that the company grew net income 17% through it, and that 16% unit growth with $1.9 million AUVs is the number that services the debt; a valuation near 22 times earnings for that combination is not obviously demanding.
What would change this
Our view is wrong if third-quarter results in late October show domestic same-store sales below the guided range or unit openings slowing, or if the company revises unit-growth guidance down. The market's reading is wrong if the five-session window recovers a large part of Tuesday's drop and October results land inside the July guidance with unit growth intact.
The tape
At the September 15 close WING was $100.84, -12.1% on the day on 2.9 million shares, a 52-week low, in the memory's state "down/below/off/stuck/effort/weak/crowd_in": a sharp break below reference levels on heavy volume with weak momentum and crowded participation [6][7]. Tuesday's move is inside the state being scored. The pre-market print at 11:31 UTC on September 16 was $101.70, +0.9%, an indication rather than a completed session [6]. Attention was broad: WING ranked ninth on the Yahoo trending list and thirteenth on Stocktwits at 07:15 ET [8].
What was filed
The proximate catalyst was third-party data: Placer.ai's August report showed nationwide dining traffic down 2.4%, relayed by the wire on the morning of September 16 as the reason for Tuesday's decline [1]. The company itself has filed nothing since the August 25 8-K; its last substantive disclosure is the second-quarter release of July 29, which cut guidance [4]. On September 11 TD Cowen lowered its price target to $120 from $160, a wire-reported analyst action [2]. Date learned: the traffic data during Tuesday's session; the guidance cut on July 29; economic event: August traffic, already complete.
The numbers around the move
The company's own numbers are the baseline. Second-quarter system-wide sales were $1.4 billion, up 5.3%; domestic same-store sales fell 7.5%; there were 102 net new openings and 16% unit growth; total revenue was $185.6 million, up 6.4%; net income rose 16.9% to $31.3 million, or $1.15 per diluted share; adjusted EBITDA rose 12.5% to $66.6 million; digital sales were 71.6% of the system [4]. Updated 2026 guidance calls for a 4-6% decline in domestic same-store sales, 15-16% global unit growth, SG&A of $140-143 million and net interest expense of about $43 million [4]. Cash was $127.5 million against $1.21 billion of long-term debt at June 27, and shares outstanding were 27.2 million on July 28 [5]. At Tuesday's close the equity was worth about $2.75 billion and the enterprise about $3.8 billion; on the first half's annualized net income of about $122 million the equity trades near 22 times earnings, against a company that grew earnings 17% in the quarter while comparable sales fell 7.5%. We did not retrieve a dated sell-side consensus. Our labelled arithmetic: the difference between a 4% and a 6% comparable-sales decline is roughly $28 million of system-wide sales, or about $1.7 million of royalty revenue at a 6% rate, against $185.6 million of quarterly revenue; the traffic print does not move that number, only the confidence around it.
What the stock did
Tuesday's -12.1% on 2.9 million shares is observed and is the event that defines the current state. The completed September 16 session is not yet observed; it will be scored after the close against the memory's 1-session band, with the Federal Reserve decision at 14:00 ET as a confounder, then the 5-session excess return by September 22.
Close update, session 1 (September 16, written after the close): WING closed at $101.06, +0.2% versus the $100.84 close of 2026-09-15, on 1.7 million shares, about 1.5 times the 20-day average; the session's range was $100.78 to $105.24 after a $102.01 open. Against the market (SPY -0.4%), the excess move was +0.7 points. Against the 1-day band from the pre-news analogs (p10 -4.2, median +0.5, p90 +7.3), that is inside the band.
The comparison
The memory's analogs describe states like Tuesday's close, after the drop: 300 analogous states across 220 symbols, with the 5-day excess band -9.1 / +1.3 / +11.3 and up 57% of the time [7]. For sharp, crowded breaks to new lows the memory has more often seen a partial rebound than continuation over five sessions, but the band is wide and is not conditioned on the cause. The company's own recent history is the better comparison: the July 29 guidance cut was the first discounting; Tuesday was the second on no new company information. Among names we have written about, CAVA fell 8.9% the same day on the same traffic data, which points at the environment rather than at Wingstop specifically.
Sources
Raw captures: the Q2 release exhibit saved under daily-trending/2026-09-16/wing/raw/; the state packet, claim and card under daily-trending/memory/2026-09-15/WING/; quotes from Yahoo bars at 11:31 UTC; the attention capture at daily-trending/attention/20260916T111501Z/ATTENTION.json. Not accessed: the Placer.ai report itself; the TD Cowen note (wire-reported); a dated sell-side consensus; X posts. Wire URLs come from ChartLibrary's news store; Benzinga pages return HTTP 403 to our fetcher.
- [1] Benzinga wire via ChartLibrary news store: 'What's going on with Wingstop stock on Wednesday?' citing Placer.ai August dining traffic down 2.4% (06:21 ET) · Available Sep 16, 2026 · 6:21 am ET
- [2] Investing.com: Wingstop price target lowered to $120 from $160 at TD Cowen (September 11, 2026) · Available Sep 11, 2026 · 10:00 am ET
- [3] Wingstop Form 8-K, July 29, 2026 (second-quarter results) · Available Jul 29, 2026 · 11:43 am ET
- [4] Wingstop fiscal second-quarter 2026 results, press release dated July 29, 2026 (8-K exhibit 99.1) · Available Jul 29, 2026 · 11:43 am ET
- [5] SEC XBRL company facts, Wingstop: cash, long-term debt, revenue, net income, shares outstanding · Available Sep 16, 2026 · 12:46 pm ET
- [6] Yahoo Finance WING chart, one-minute bars including pre-market, and daily bars · Available Sep 16, 2026 · 7:31 am ET
- [7] ChartLibrary state packet, WING as of the September 15, 2026 close · Available Sep 16, 2026 · 7:45 am ET
- [8] Alphaforge attention capture, September 16, 2026 07:15 ET (Stocktwits and Yahoo trending lists) · Available Sep 16, 2026 · 7:15 am ET
Live situations, scored after the close. Not a buy list.
The daily note is free and stays free. Follow @ChartLibraryio.
Publication history
- Revision 1 · Sep 16, 2026 · 12:53 pm ET · Initial publication
- Revision 2 · Sep 16, 2026 · 4:19 pm ET · Close update, session 1: completed session versus the framing and the analog band